Business Account The unified account layer for stablecoin-enabled businesses
Learn more
Embedded Finance Launch branded financial products on Reap's infrastructure, one API integration
Learn more
Money Movement
Agentic Payments Agentic spends on any merchant, anywhere. Agent-native checkout live today.Explore
One stack, direct or embedded.See pricing

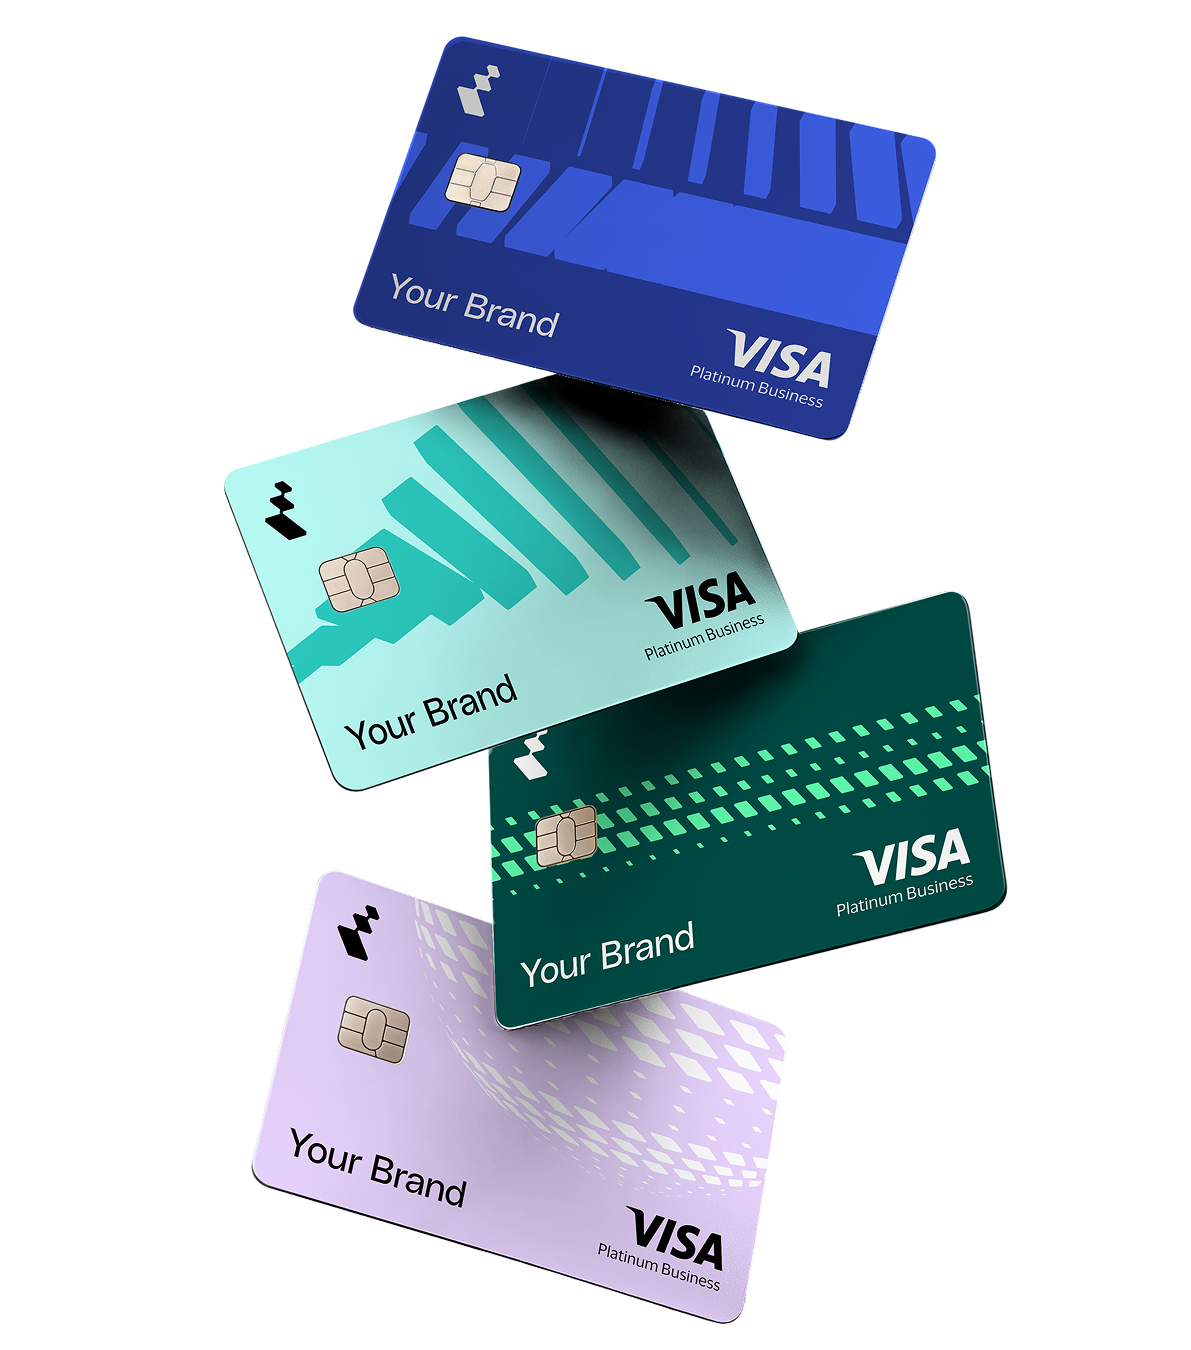
Issue your own cards. Spend anywhere Visa is accepted.

Launch and scale your branded card program on Reap's Visa principal issuing licence. Reap handles the program. You focus on growth.

8+ years
In the card issuing business
8+ years
In the card issuance business
2M+
Cards issued
175M+
Merchants worldwide
Visa Principal Issuer
Hong Kong and Mexico. Credit BINs.
2x+ lower
Fraud loss rate than industry benchmarks

TRUSTED BY

WHY CARD PROGRAMS STALL

Card issuing is a
full-stack operations problem.

Every platform that tries to launch a card program faces licensing, compliance, vendor coordination and ongoing operations that most teams underestimate.
What a card issuance program actually requires

Licensing & scheme access

Get Visa membership/BIN sponsorship (either become a principal issuer or secure a sponsor).

Compliance & onboarding stack

Build KYC/KYB that satisfies both regulators and the card scheme.

Card production & lifecycle logistics

Handle card design/production/
personalisation
, global shipping, inventory, replacements, and returns.

Ongoing risk + operations backbone

Run fraud/risk management, disputes & scheme compliance, plus reconciliation/settlement and day‑to‑day program ops/support.

WHAT IS INCLUDED in a card issuing service

One card issuing platform. Everything the program needs.

As a Visa Principal Issuer, Reap provides one integration, one single API. Fund your program in stablecoins or fiat. Let your users spend digital assets or local currency. Settle with Visa daily.

Visa principal issuing licence
Credit BINs
Virtual and physical card issuing
End-to-end program operations
Developer-first card issuing API
Daily Visa settlement

Visa principal issuing licence

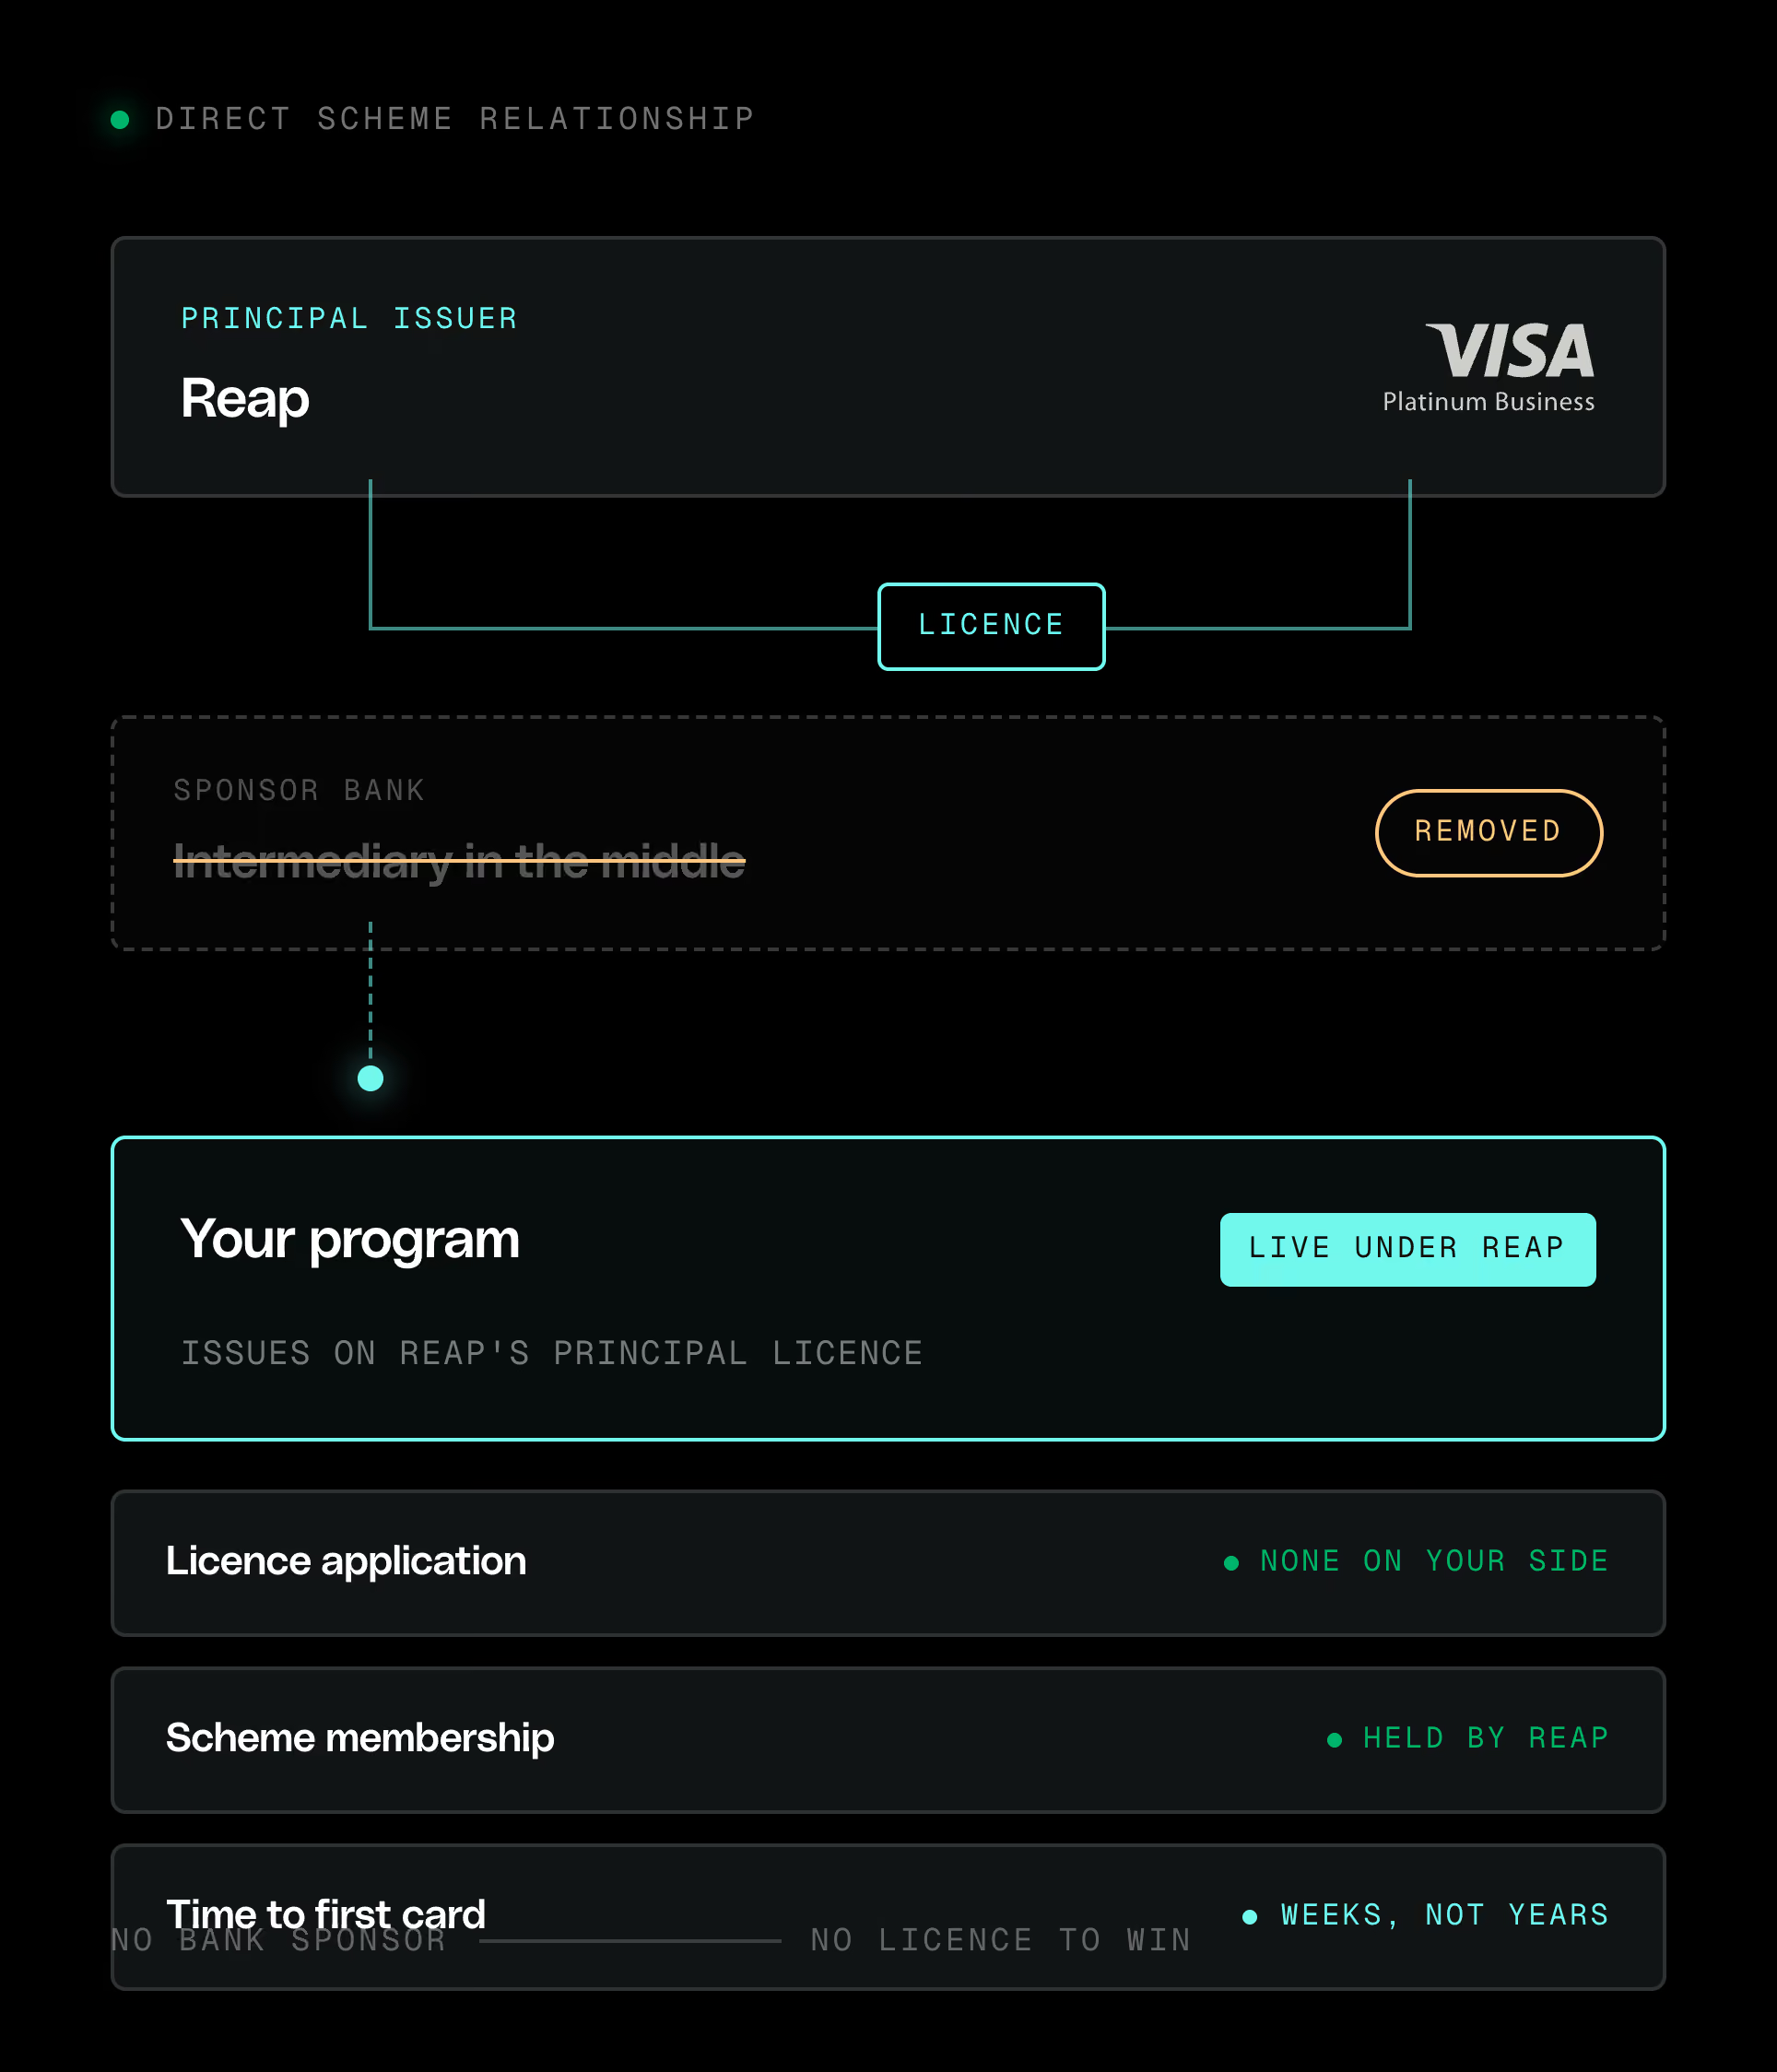
A direct scheme relationship, no bank sponsor in the middle. You operate under Reap's principal issuer status with no licence application on your side.

They have top notch infrastructure, great tech, and an amazingly supportive team. They're one of the few in the industry that truly get it and want to help you succeed.

jon low, ceo

THE API

Card issuing API:
issue, manage and control cards programmatically

One integration issues virtual and physical cards, sets spend controls, streams transactions and handles disputes. Sandbox first, production when you are ready.

Issue virtual cards instantly and order physical cards through the same API

Fund directly with USDC or USDT. Send payments in 18+ fiat currencies to 220+ countries. No bank required.

Read the API docs

Set spend controls, MCC restrictions and limits per card or per cardholder

Issue Visa credit cards to your whole team in minutes. Virtual or physical. Fund directly from your stablecoin balance. Set spend limits and approval workflows per cardholder. Accepted at 60M+ Visa merchants worldwide.

Scoped tokens so your services only reach what they need

Send USDC or USDT from anywhere. Recipients receive in 40+ fiat currencies across 220+ countries. No conversion friction.

Webhooks for authorisations, transactions and disputes

Approval workflows, spend controls, receipt capture. Integrations with Xero.

Apple Pay and Google Pay provisioning from day one

One treasury for your stablecoin balance. Fund cards, payments, and expenses directly across Ethereum, Polygon, Solana, and TRON. No more patchwork tools. No more spreadsheets.

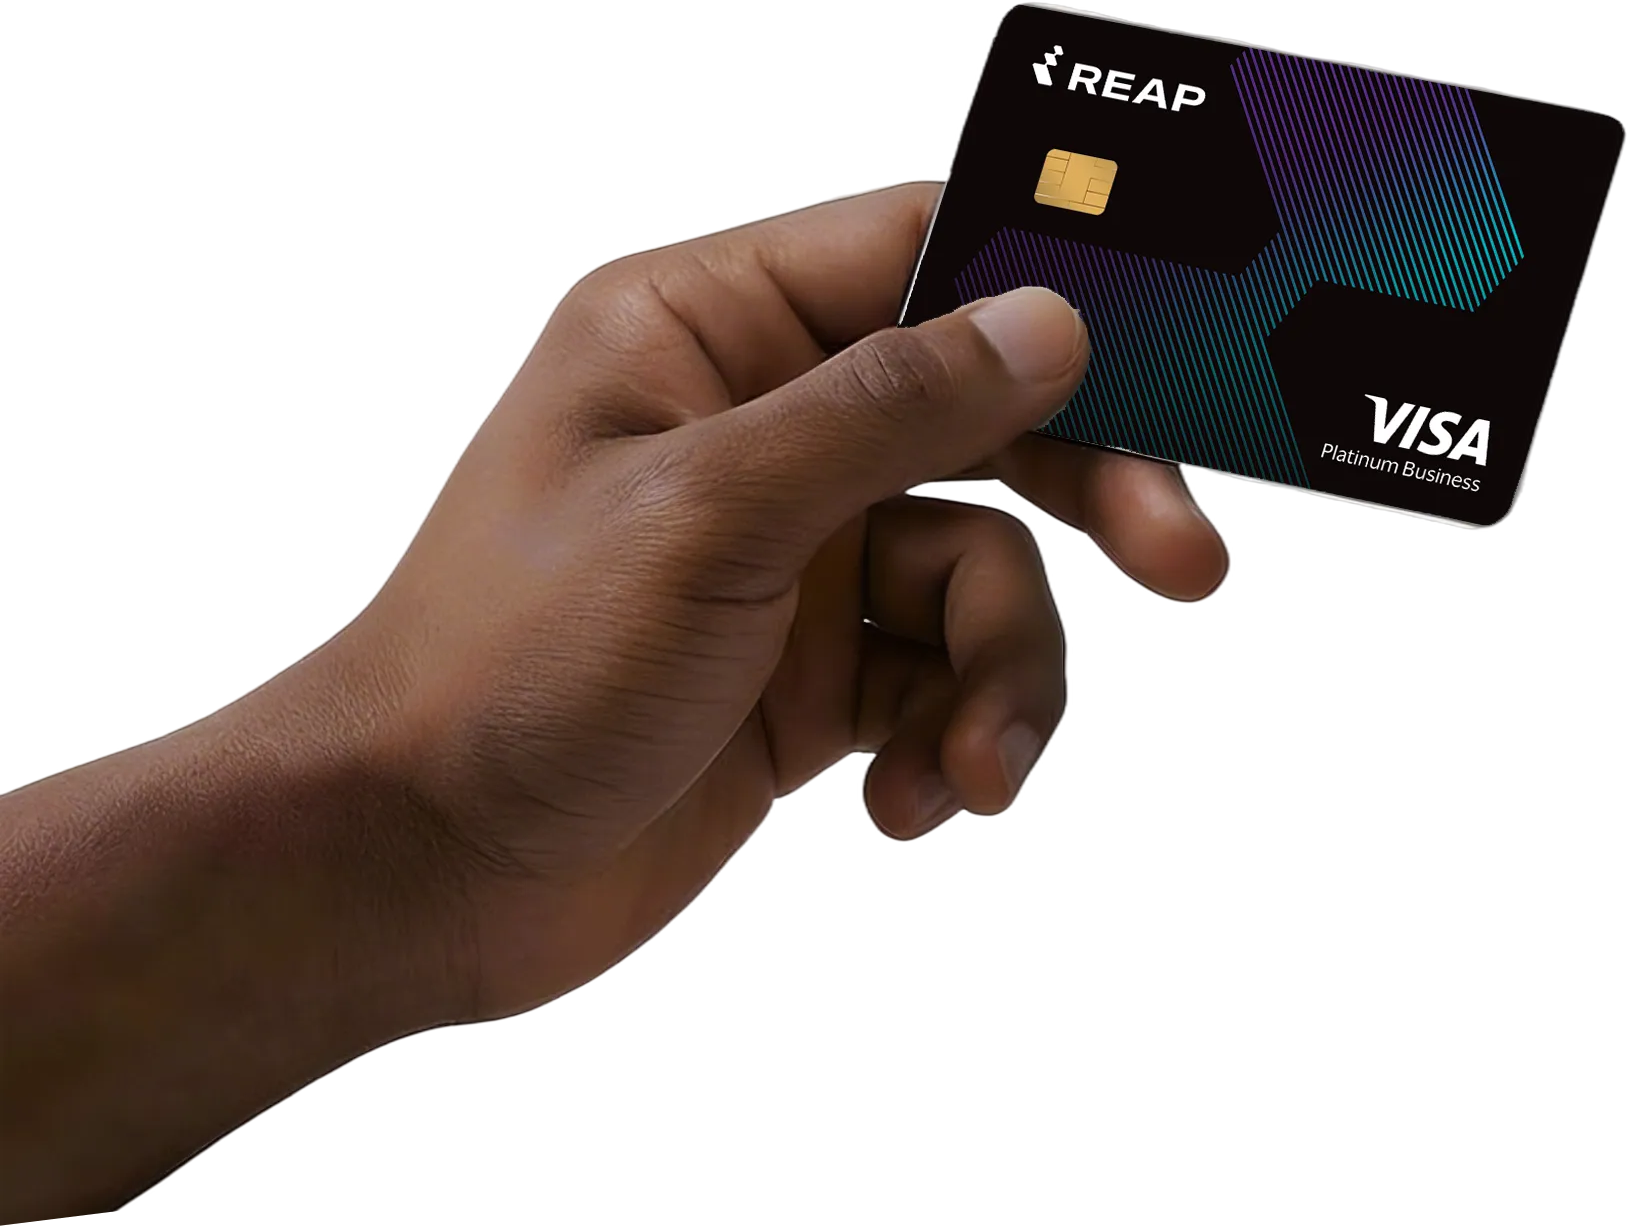
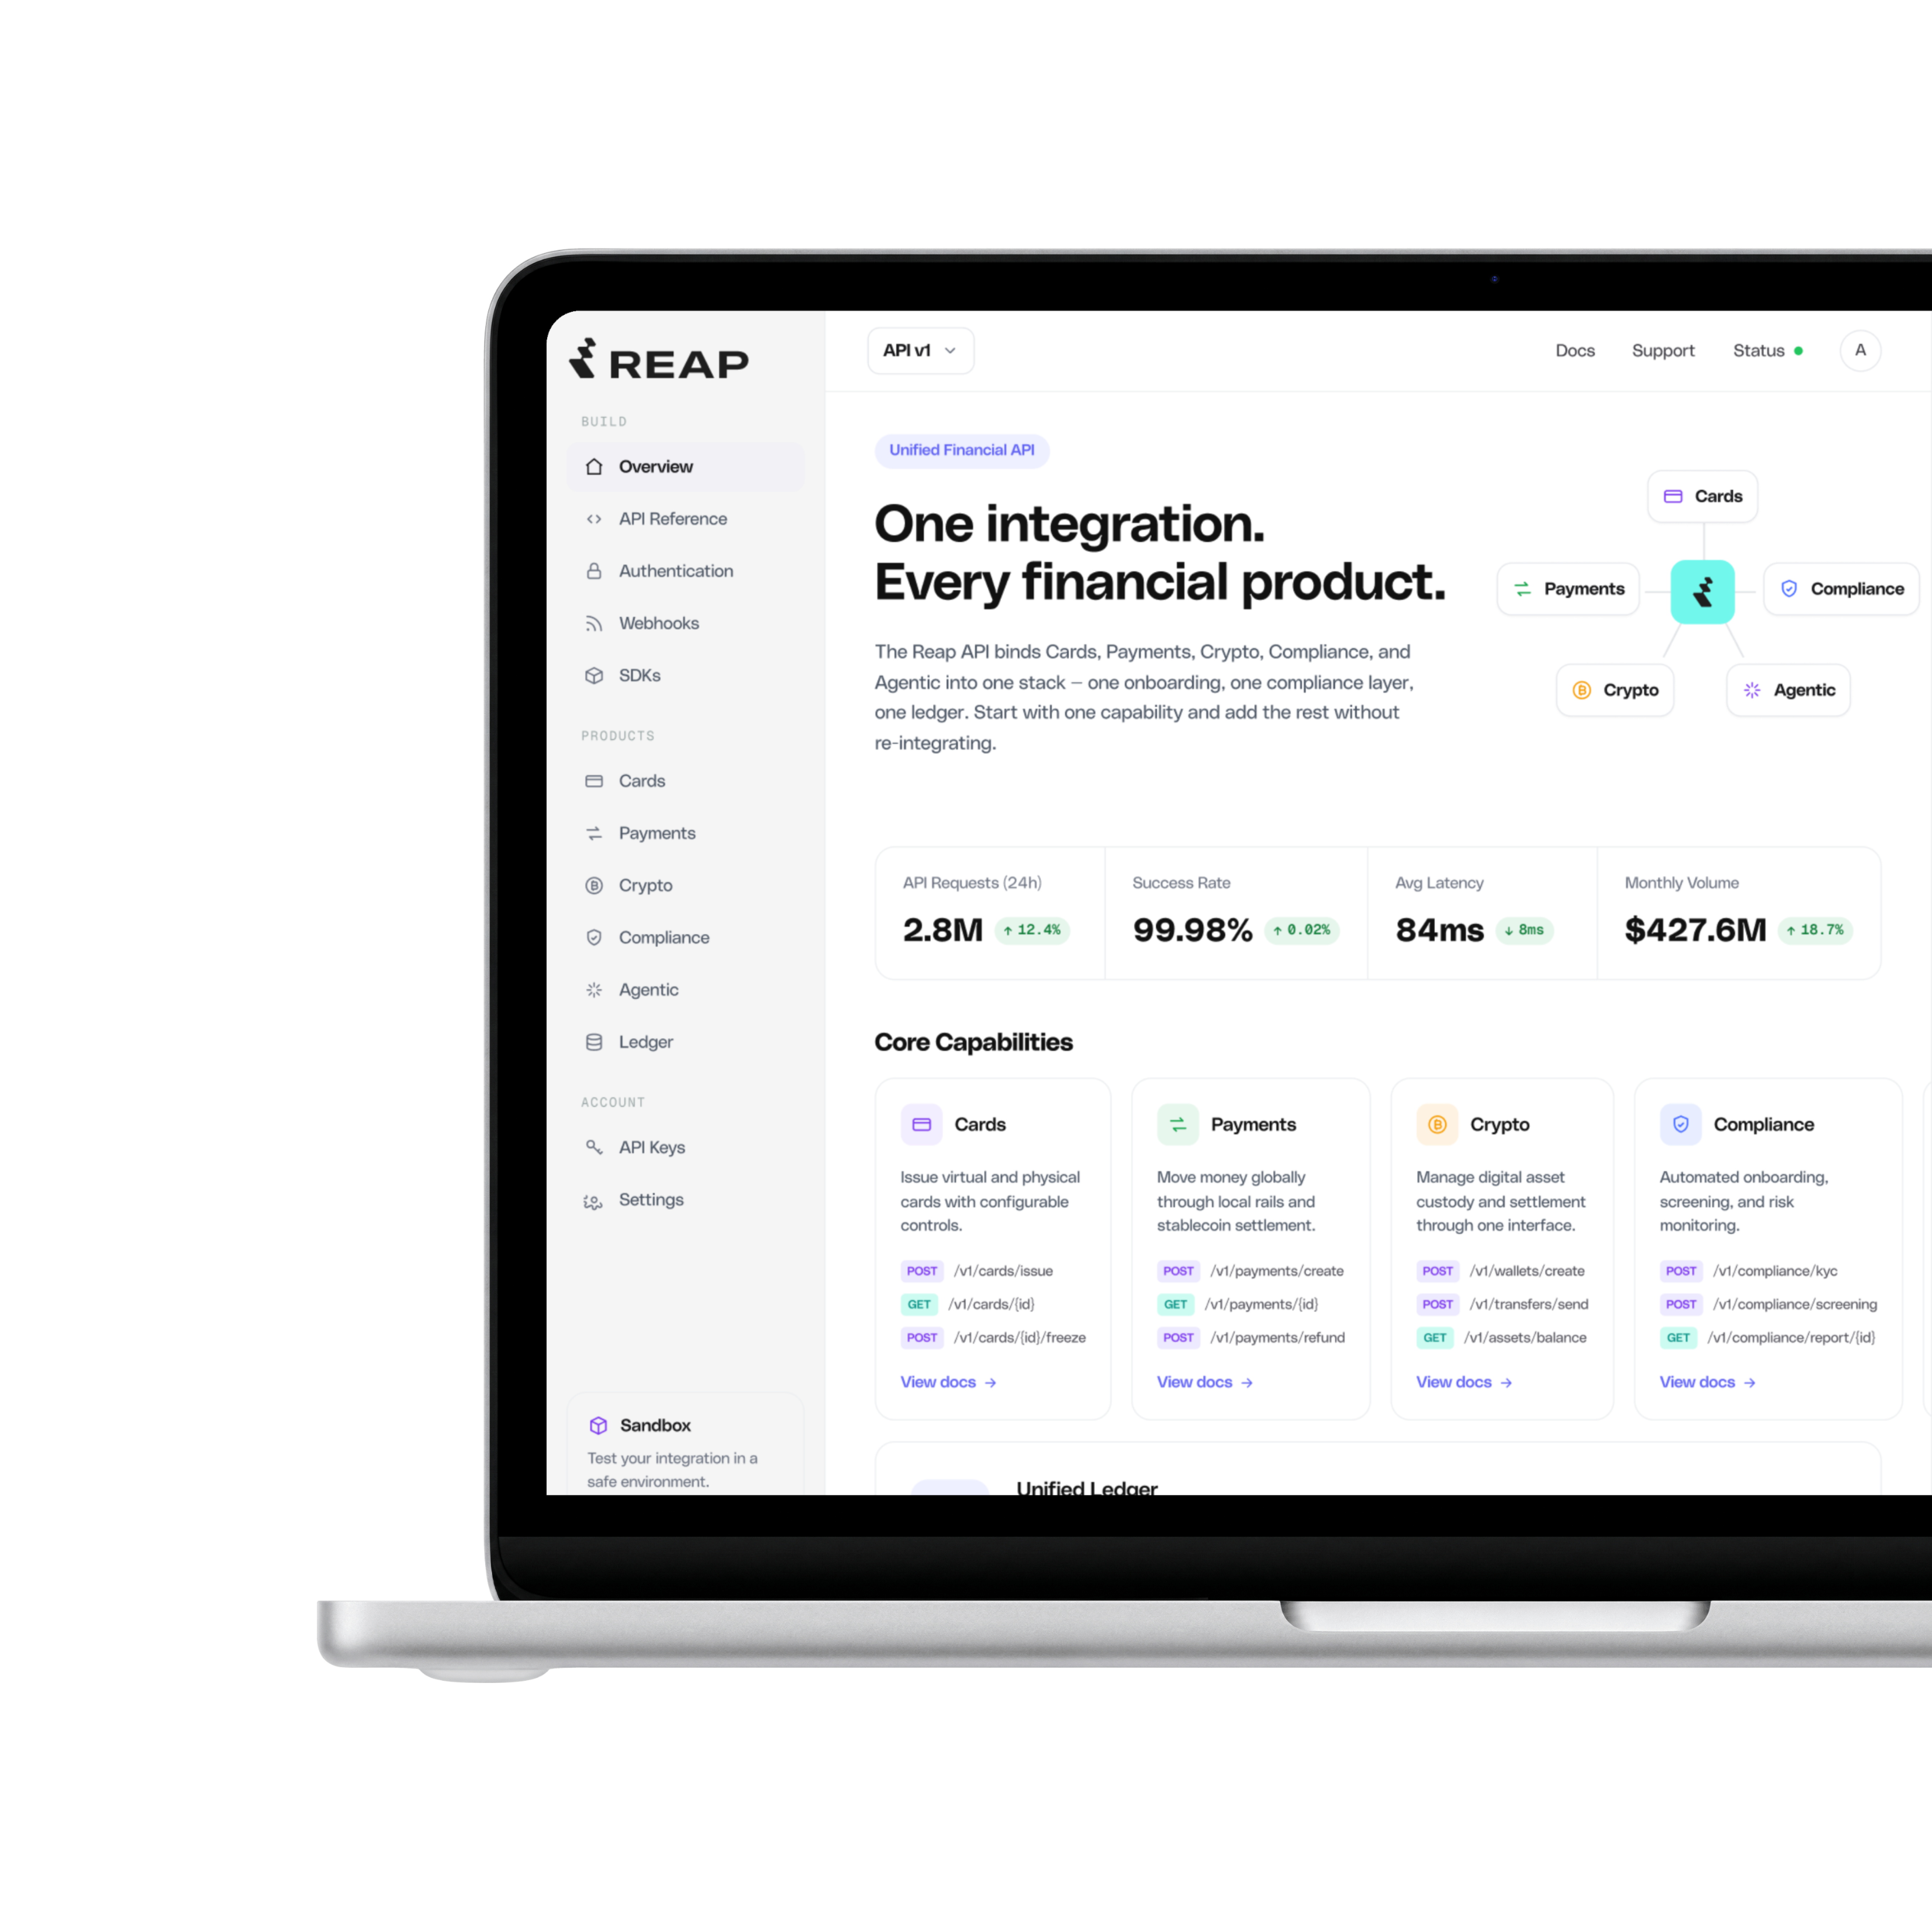
Hand holding a Reap Visa corporate cardReap dashboard on a laptop

DIGITAL ASSETS

Launch crypto-native cards. Make any digital asset spendable.

Your users can hold more than just stablecoins.
You decide what they can spend

USDC, BTC, ETH, yield-bearing tokens, loyalty points, or credit. All runs through one integration and one main account, with no extra funding flows to manage.

It converts at checkout. No off‑ramp, no swaps. You just tap and spend.

MODULES

Four modules included in every card issuing program

What running a card program safely requires

Reap Sentry, managed risk

Reap helps protect your card program with fraud monitoring, dispute support and Visa compliance managed by our risk team.

CHECK IT OUT

Virtual Assets

Let users spend stablecoins, major crypto, yield-bearing tokens or points through one simple integration.

CHECK IT OUT

Reap Rewards

Add lounge access, perks and loyalty to your card without building new rewards infrastructure.

CHECK IT OUT

BIN sponsorship

Run more of the card program yourself while Reap provides the Visa BIN and scheme relationship.

CHECK IT OUT
AGENTIC PAYMENTS

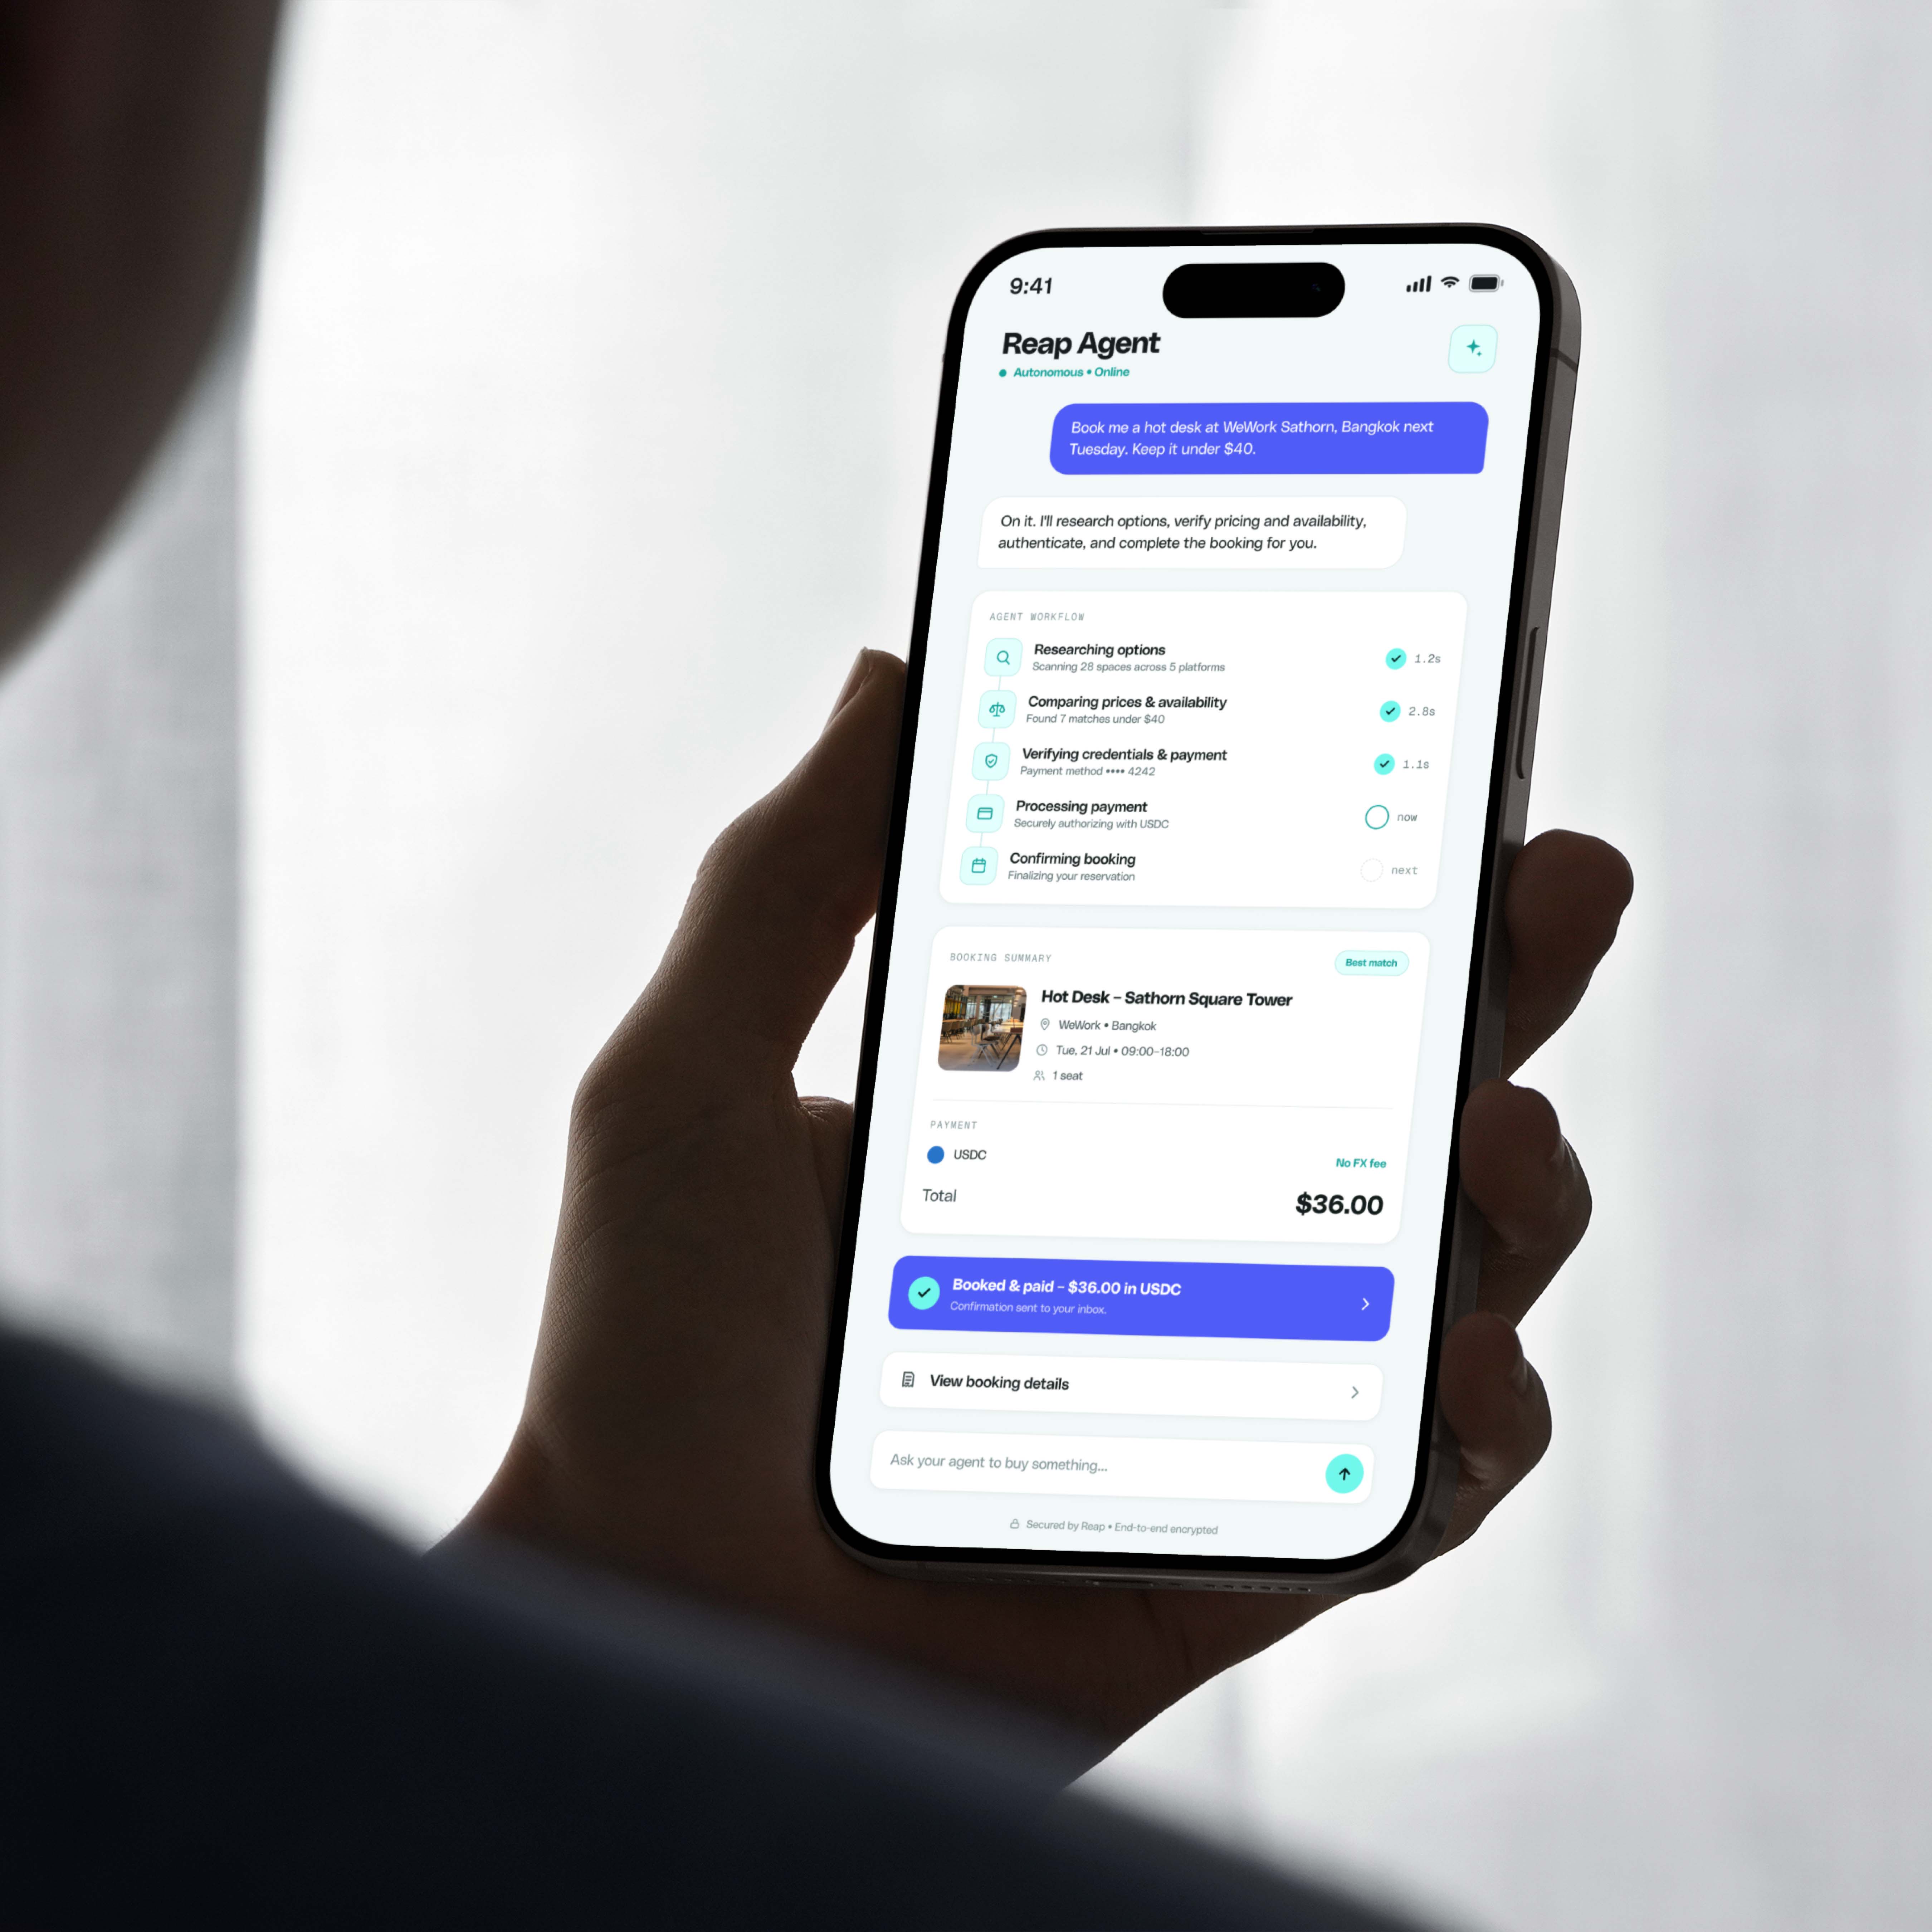
Give your cards to AI agents

Any AI assistant can make purchases anywhere cards are accepted: you can set spending rules and limits, reduce fraud risk, and keep the card details hidden from the AI, all without needing to become a card issuer yourself.

minted on intent

bounded by policy

auto-retires

CHECK IT OUT
USE CASES

Card programs built on Reap

Whether you are issuing your first card or scaling a live program, the risk work is the same and it is the part nobody wants to build twice.

One spend rail for any asset

01 For

Neobanks & Digital banks

Add cards to your financial product. Your users can store value with you and spend it every day. You manage onboarding, card controls and notifications. Reap runs the infrastructure behind it.

01 For

Fintechs & Financial institutions

Add card issuing to your product without building the full stack yourself. Use Reap's principal licence, managed risk and card operations while keeping the customer relationship.

01 For

Centralized exchanges

Let holders spend every day without asking them to off-ramp. Users tap and spend stables, BTC, ETH or yield-bearing tokens directly. More use, more stickiness, more revenue per user.

01 For

Web3 & DeFi platforms

Let users spend from staked tokens, vault shares or LSTs without unstaking first. Launch a crypto card that lets them keep earning yield until they tap.

01 For

Advertisers & Media buyers

Your customers spend millions on digital ads. Give them unlimited virtual credit cards that keep ad campaigns live.

How it works

Get started in 4 steps

01

Talk to our team

We align on target markets, use case, cardholder profile, funding model and business goals, then define the program blueprint together.
02

Sign and verify

You complete KYB and provide program documentation. Reap runs compliance checks and finalises scheme approvals. No licence application on your side.
03

Test and integrate

Build your card experience in the sandbox. Configure spend controls, dispute processes and card production logistics. Test end to end.
04

Go live and scale

Issue your first cards, then scale globally.

What you do vs. what Reap does

You
Reap
Choose assets and pricing
Authorises spend against available balance
Maintain user balances (deposits/withdrawals/repayments)
Clears, reverses, and settles transactions
Fund the master collateral account
Holds the master collateral account
Keep custody and the user relationship
Polls your pricing feed for dynamic-rate assets
Applies your balance updates atomically
FAQ

Questions platforms ask before
launching a card program

+01
What is Reap Card Issuing?
Reap Card Issuing is a full-stack card issuing platform and API for branded card programs. Reap is a Visa Principal Issuer in Hong Kong and Mexico, which means you launch on Reap's licence without applying for your own. One integration covers the BIN, processing, card design and production, KYC and KYB, fraud monitoring, dispute handling, reconciliation and ongoing program operations, across 100+ markets.
+02
What is the difference between a card issuing API and a card issuing platform?
A card issuing API is the interface you build against: create cards, set controls, read transactions. A card issuing platform is everything behind it: the scheme licence, the BIN, processing, card production, KYC, fraud monitoring, disputes, reconciliation and settlement. Most providers sell the API and leave the platform work to you. Reap provides both, because Reap is the issuer rather than a layer on top of one.
+03
Which digital assets are supported?
For program funding, USDC and USDT. For user-level spend, any asset you can define and price: stablecoins, BTC, ETH, yield-bearing tokens, loyalty points and credit lines.
+04
Can you issue and support cards globally?
Cards are issued out of Hong Kong and can be used in 100+ markets.
+05
Why launch a credit card instead of a debit or prepaid card?
Credit cards offer better fraud protection, chargeback support and global acceptance, including at merchants and MCCs that often block debit or prepaid. Credit BINs also unlock more interchange revenue for your program.
+06
How long does it take to launch?
Most clients go live in 2 to 3 months after KYB, covering onboarding, integration, testing and deployment. Fast engineering teams have launched in as little as 2 weeks.
+07
Do I need to build a risk or fraud team?
No. Every Card Issuing program includes Reap Sentry, Reap's managed risk service. Your program is protected from transaction one with no risk hires and no fraud tooling on your side.
+08
What is the difference between Card Issuing and BIN sponsorship?
Card Issuing is the full-stack program: Reap handles everything from the BIN to card production to risk to ongoing operations. BIN sponsorship is for larger platforms that want to run more of the program independently, handling their own KYC, KYB, program management and operations while Reap provides the Visa BIN and scheme relationship. The right path depends on your team's operational maturity.
+09
Can my users spend digital assets natively?
Yes. You define the asset, set the rate or point to your price feed, and users spend it on their card. Conversion happens at the point of sale, with no swapping or off-ramping on the user's side.
+10
Can I offer loyalty and rewards through my card?
Yes. Reap Rewards gives you API access to premium benefits including airport lounge access, with cashback, merchant offers and other reward types on the roadmap.
+11
Can AI agents spend on cards I issue?
Yes. Reap's agentic payments infrastructure lets an AI agent complete a purchase at any merchant with spend bounded by policy and fraud contained, without exposing card data to the model. You do not need to become a card issuer to offer it.
+12
What does it cost to build a card program in-house instead?
Most platforms spend 12 to 18 months and millions assembling an issuer, a processor, a scheme relationship, KYC and KYB vendors, card production, disputes, reconciliation and risk management before issuing a single card. Risk alone runs to ~USD 250K: a real-time monitoring platform at ~USD 150K and a fraud specialist at ~USD 100K/yr.
Get Started

Launch your card program on Reap

Join our Agentic Accelerator Program Learn more